Buying auto insurance at a dealership: What’s changing

Published on October 23, 2026
5 mins reading time
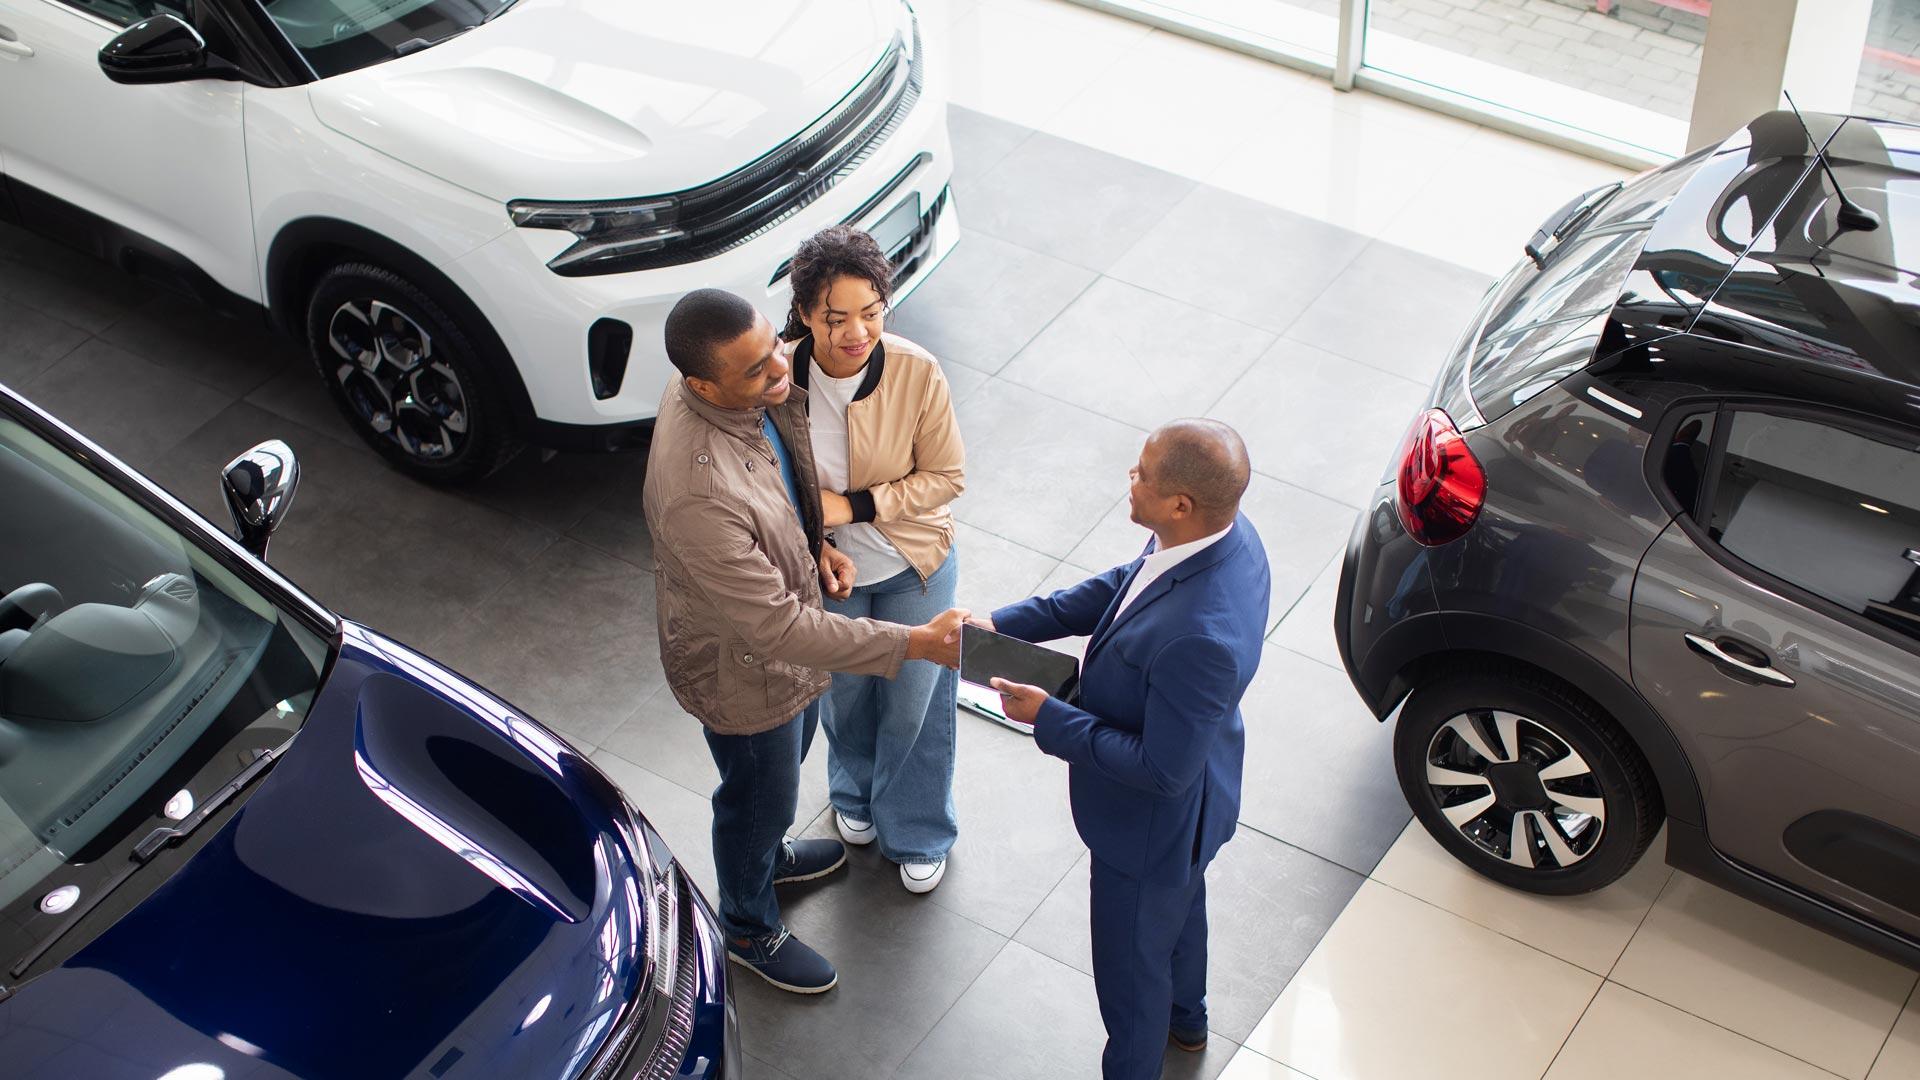
A car salesperson congratulates a couple who just bought a car

Buying a car from a dealership isn’t just about choosing a model and negotiating the price. Financing, insurance and other financial products can also be part of the transaction. New rules now govern some of these products and strengthen protection for buyers, offering them greater peace of mind. Here’s what changes in practical terms.

What’s changing for auto insurance?

The main change resulting from the adoption of Bill 30, An Act to amend various provisions mainly with respect to the financial sector, concerns replacement insurance (Q.P.F. No. 5) sold at dealerships. As of January 1, 2027, Quebec dealerships that sell automobiles and recreational and leisure vehicles will no longer be able to offer or sell this insurance in connection with the purchase or lease of a vehicle. The measure aims to better protect consumers and reduce decisions made under pressure.

Replacement insurance is separate coverage from your auto insurance. It allows you to receive, following a covered loss, a payout that doesn’t factor in your vehicle’s depreciation.

Previously, dealerships could offer this insurance directly to vehicle buyers. This protection isn’t disappearing, however. You’ll still be able to get replacement insurance from an auto insurance agent or broker.

Which types of insurance can dealerships still offer?

Dealerships can still offer certain protections:

  • Life insurance, which can pay off the car loan balance in the event of death
  • Disability or illness insurance, which can help you make payments if you can no longer work
  • Job loss insurance, which can help repay the loan in certain situations

However, as of July 1, 2026, you must be able to pay the insurance premium annually rather than paying a single premium for the entire term of the contract. This measure is meant to prevent the single premium from being included in the vehicle financing.

What do these changes mean for consumers?

The goal of these changes is to strengthen oversight of financial products and give consumers better protection and financial security.

For you, this mainly means it’s important to clearly distinguish between the price of the vehicle, the financing and the insurance protections. Take the time to understand what’s mandatory and what’s optional, what each protection covers and how much it will cost you before adding it to your contract. A “small” $2000 can quickly climb to $2500, or even $3000, if the vehicle is financed over a long period of time.

What to check before you sign when buying a car

Before finalizing your purchase, take a few minutes to:

  • Check the protections and warranties covering repair costs offered as part of the financing. Remember that you can decline the ones that don’t suit you.
  • Compare the protections and coverage amounts offered with those proposed by your insurer or another insurance professional.
  • Read all documents carefully, including the terms and conditions, before signing.
  • Ask questions if a protection or financial product isn’t clear.
Pro tip

“A lower monthly payment doesn’t necessarily mean you’re getting a better deal. To compare offers and financing options, ask for the price of the vehicle, the cost of financing, and the cost of protections separately.”

Jesse CaronAutomotive Expert, CAA-Quebec

Other recent changes also strengthen consumer rights when it comes to motor vehicles. Learn more about your rights and recourse under Bill 29, An Act to protect consumers against planned obsolescence and to promote the durability, repairability and maintenance of goods, and about the anti-lemon warranty.

FAQ – Frequently asked questions about auto insurance and auto financing

1. Can you still buy replacement insurance at a dealership?

Yes, until December 31, 2026. As of January 1, 2027, dealerships will no longer be able to distribute this insurance. However, you’ll be able to get replacement insurance from an insurance agent or broker.

2. Where can you buy replacement insurance?

Replacement insurance can be offered by a damage insurance agent or broker.

3. What is replacement insurance?

Replacement insurance is separate coverage from your auto insurance. It allows you to receive, following a covered loss, a payout that doesn’t factor in your vehicle’s depreciation.

4. What financing-related insurance can a dealership offer?

Life, health or job loss insurance tied to the repayment of an auto loan can continue to be offered by dealerships under certain conditions. Some rules have been tightened, however, particularly for contracts longer than one year.

5. Does the adoption of Bill 30 make the price of a car clearer?

Yes, in part. The new rules aim to better separate the price of the vehicle, the cost of financing and the cost of insurance and other protections offered at the dealership. This way, you can better understand what you’re paying and compare the different options before you sign.
Looking for advice or coverage for your vehicle?

Do you have questions about gas-powered or electric vehicles, driving, or need recommendations to find an Approved Auto Repair Service?

To ask your questions
1-888-471-2424

See how our Auto and Vehicle Insurance can meet all your needs!

To ask your questions:
1-844-446-3636